Apply online
Share the entity, amount, and use of funds. Soft inquiry to start. You are not accepting terms by sending the form.
Small-business funding
Compare eight funding structures in one application. We review deposits, match a facility your cash cycle can service, and say no when it cannot.
Applying is free and designed as a soft inquiry. This is a review request — not an offer of credit.
Funding products
Each card carries an honest spec chip — amount style, term style, or speed frame — not a guaranteed approval. One application covers the set.
Revolving capacity you draw when deposits dip — and repay when they recover.
Revolving · Draw as needed Learn more →
A defined amount on a defined clock for near-term gaps and purchases.
Defined term · Lump sum Learn more →
Larger amounts with longer terms when the use should outlast a busy quarter.
Multi-year · Planned use Learn more →
Advance against billed, unpaid work instead of waiting on net-30 or net-60.
Advance on receivables Learn more →
When the asset is the plan — trucks, machines, kitchen lines, shop tools.
Asset-backed · Vendor invoice Learn more →
An advance against future card or ACH deposits, repaid as a share of intake.
Deposit-tied · Faster path Learn more →
Capital repaid as a percentage of revenue so payments flex with the month.
Flex with revenue Learn more →
Longer, often cheaper paths through partner lenders. We are not the SBA.
Longer docs · Partner lenders Learn more →How it works
No same-day guarantees. The work is matching a facility to deposits you already have.
Share the entity, amount, and use of funds. Soft inquiry to start. You are not accepting terms by sending the form.
We review statements, existing obligations, and whether a quiet month can still service the facility.
When a source can underwrite it, terms are written before anyone signs. Timing depends on the product — days for some, weeks for others.
Why Oak Harbor
We built the process around deposits and repayment math — not invented volume claims or award walls.
Recent activity and existing obligations come before the product name on the card.
Line, term, factoring, equipment, merchant, revenue-based, or SBA — matched to the use of funds.
Cost, holdbacks, guarantees, and default language are discussed before a signature.
We would rather say no than force a facility whose repayment fights the cash cycle.
Industries
Fourteen verticals with real operating photos — restaurants, crews, clinics, fleets, shops, and more. The deposit pattern is the underwrite.
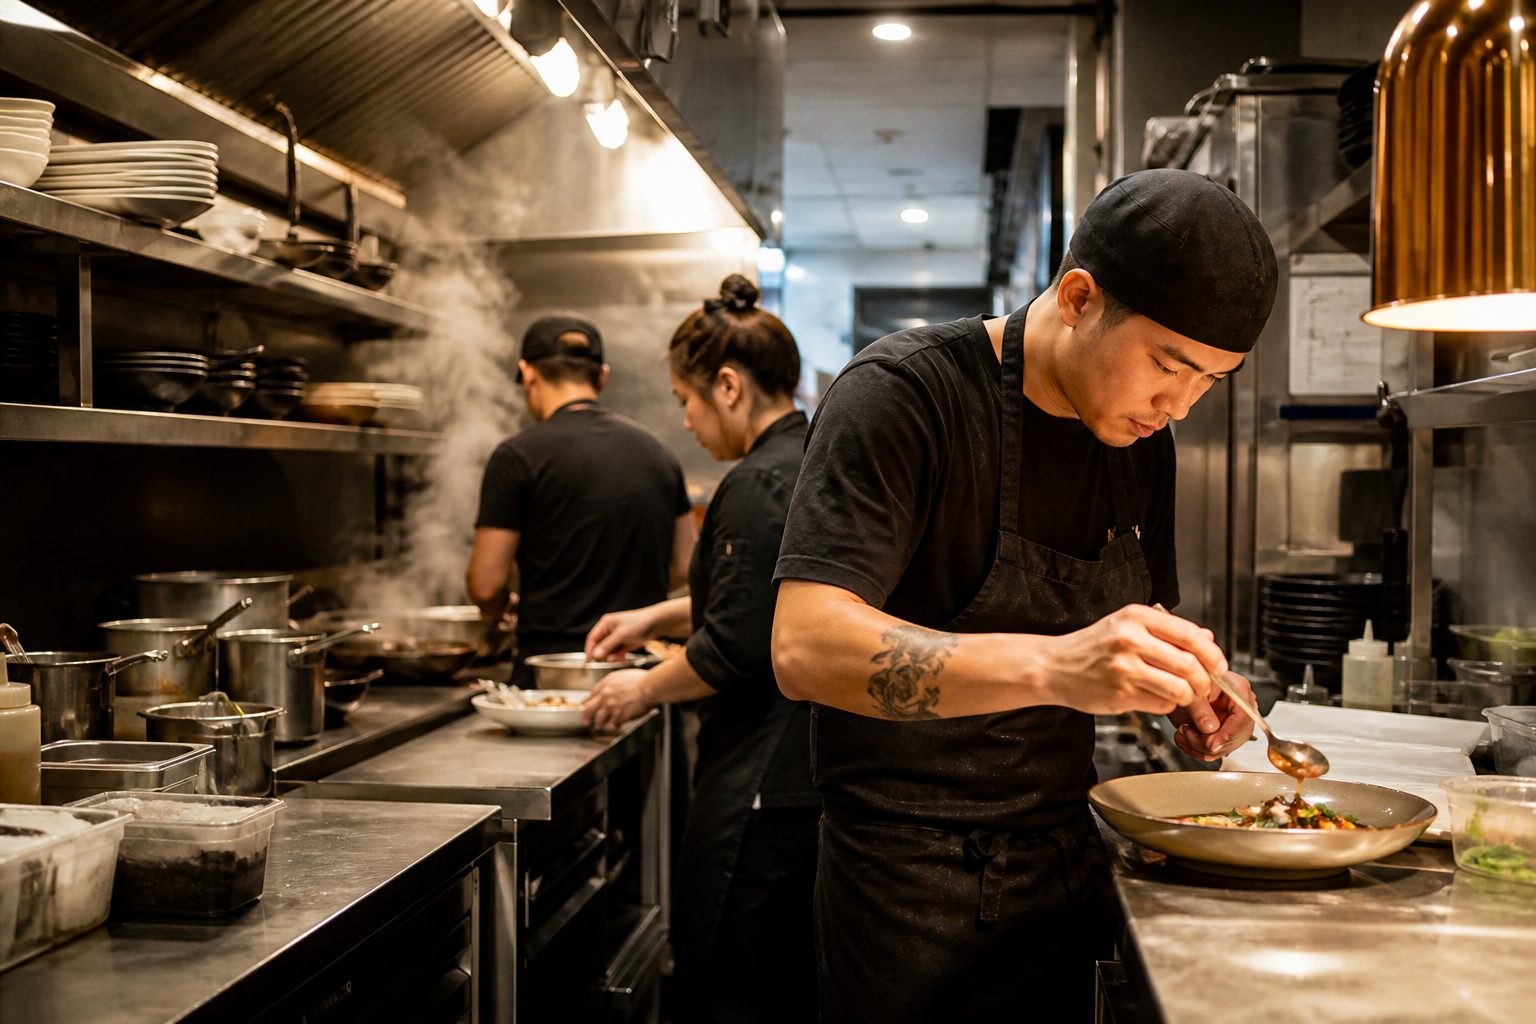
Inventory, payroll, and the Tuesday after a holiday rush.
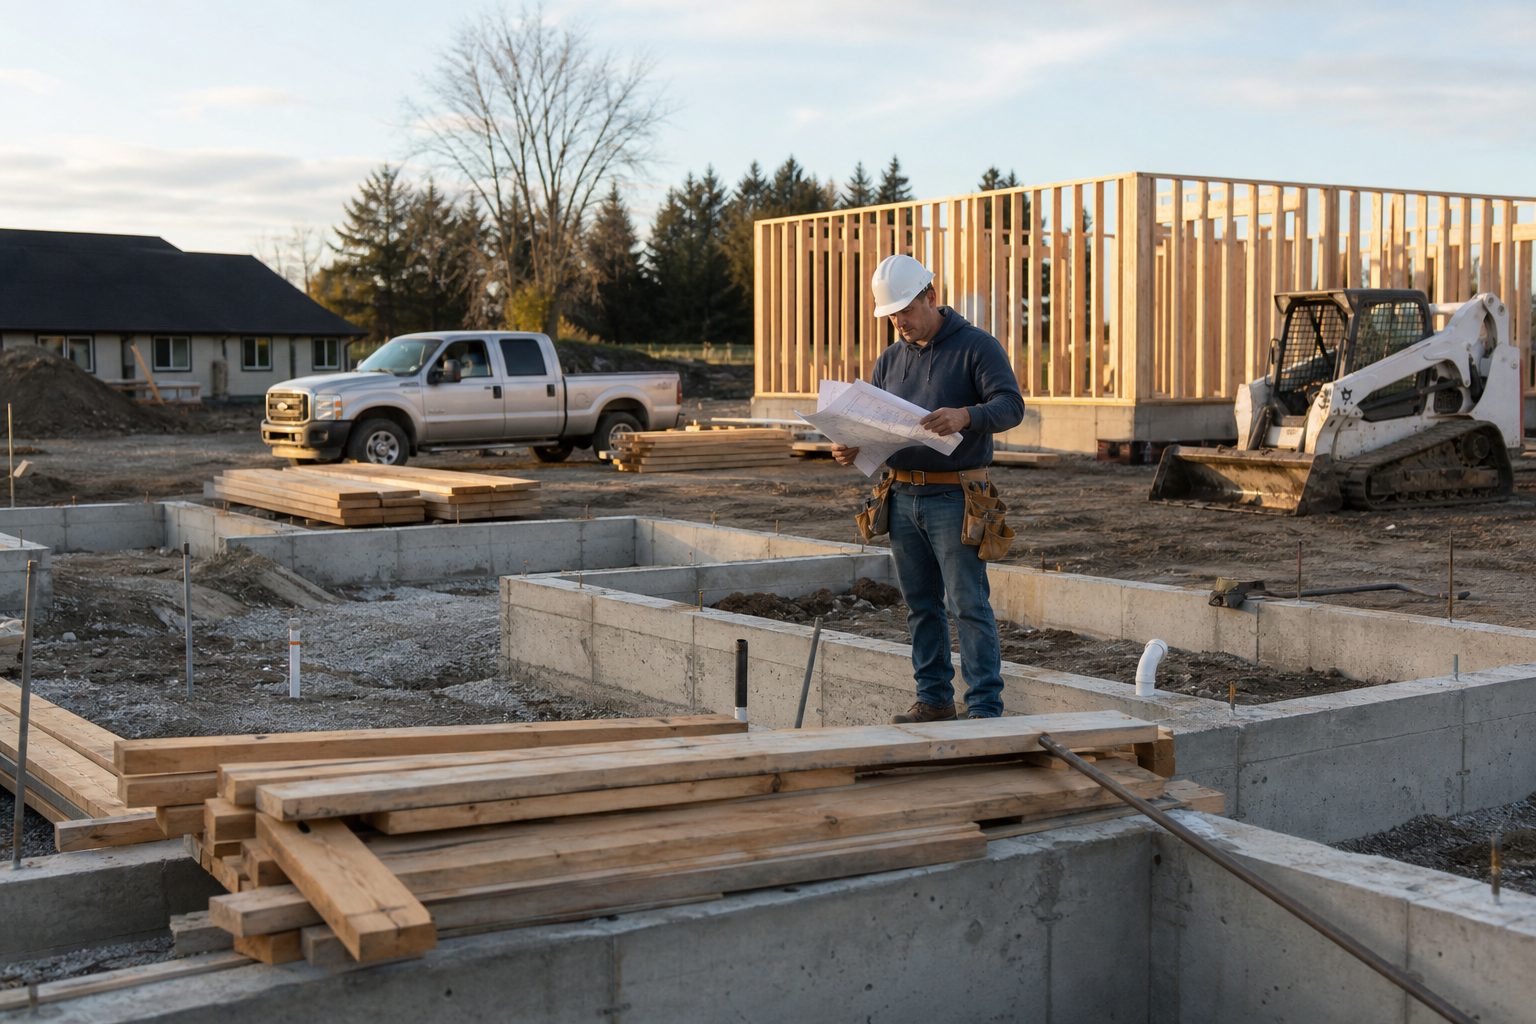
Materials and labor on someone else's draw schedule.
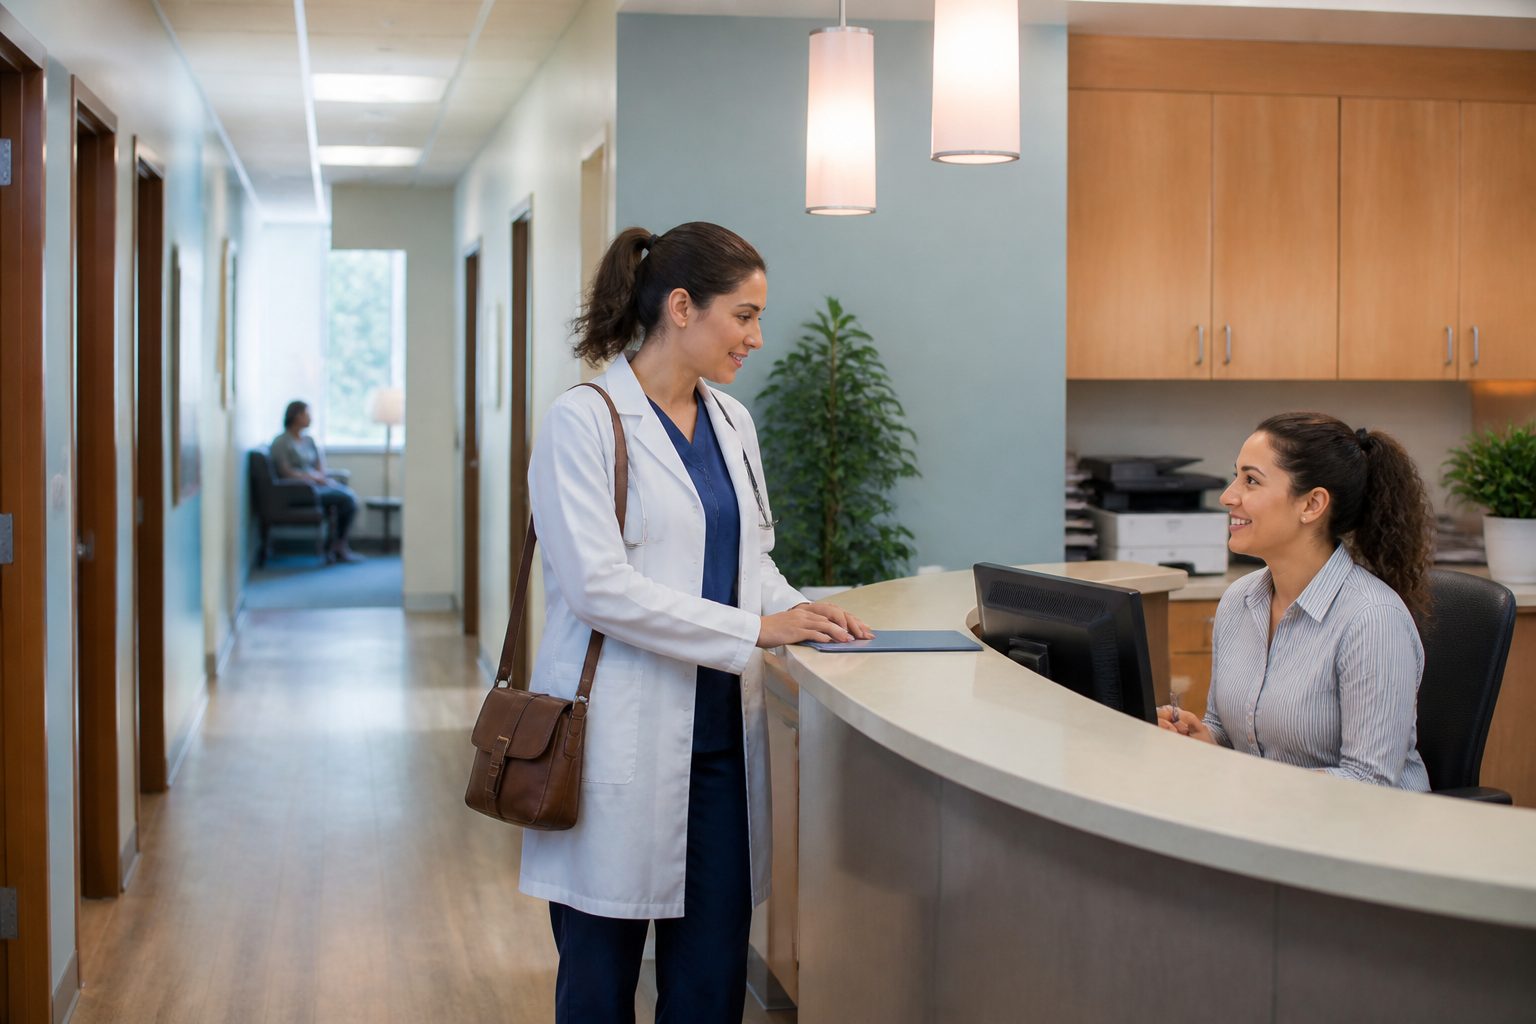
Staffing and equipment while payers catch up.
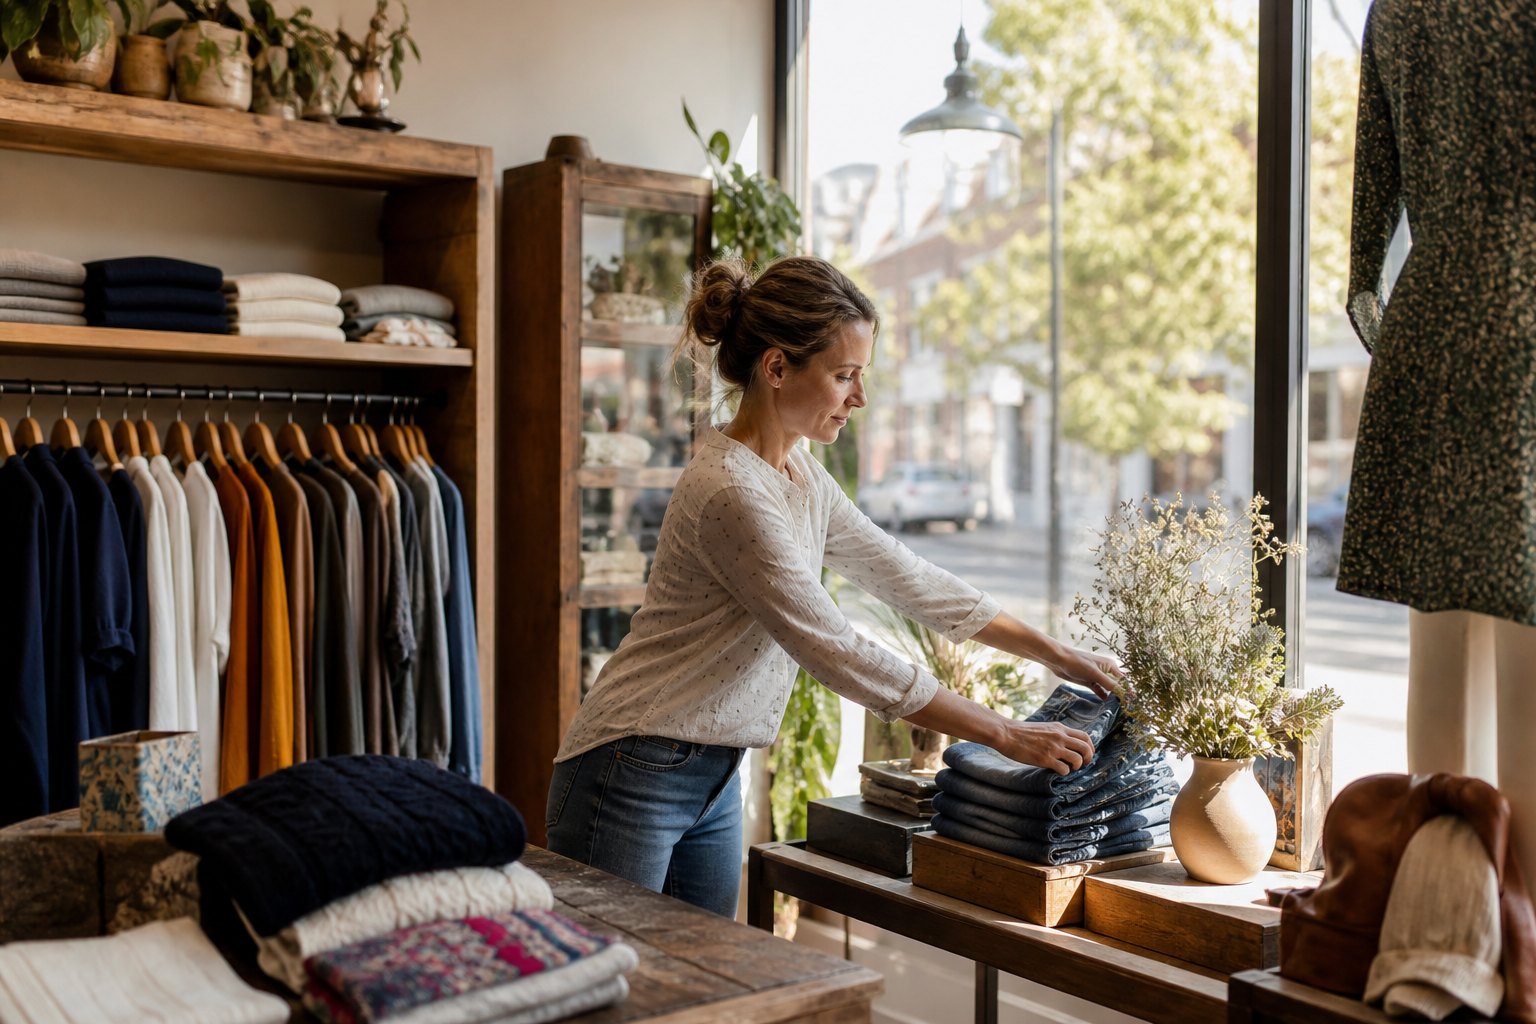
Inventory that has to turn before the next invoice.
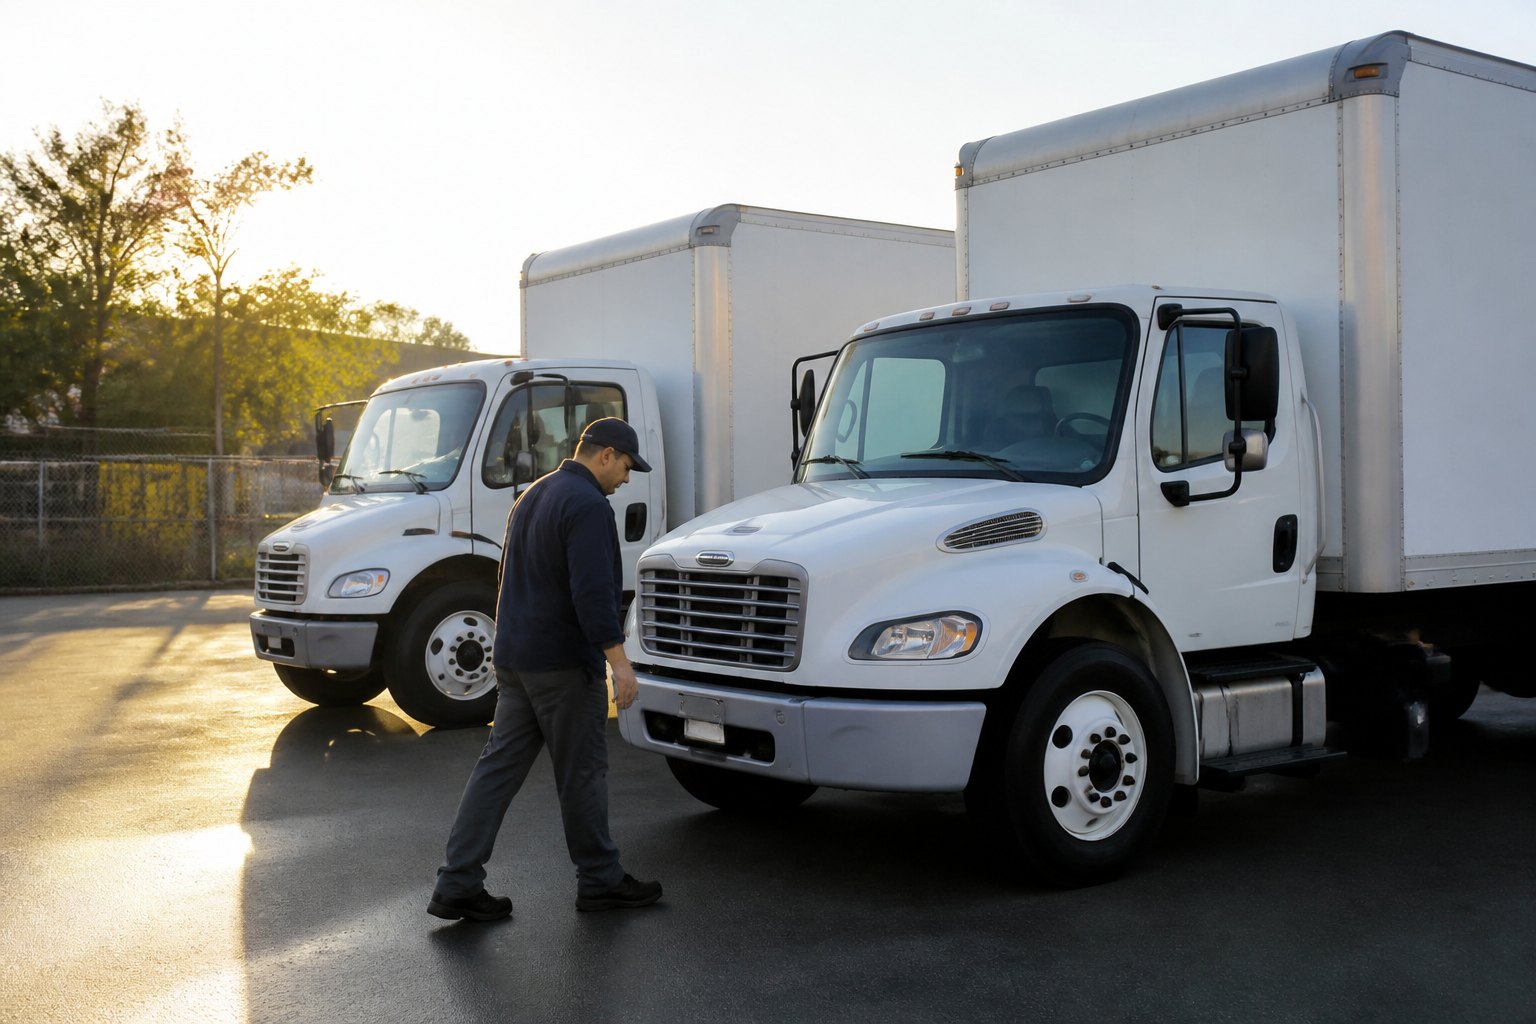
Fuel, freight, and maintenance while settlement waits.
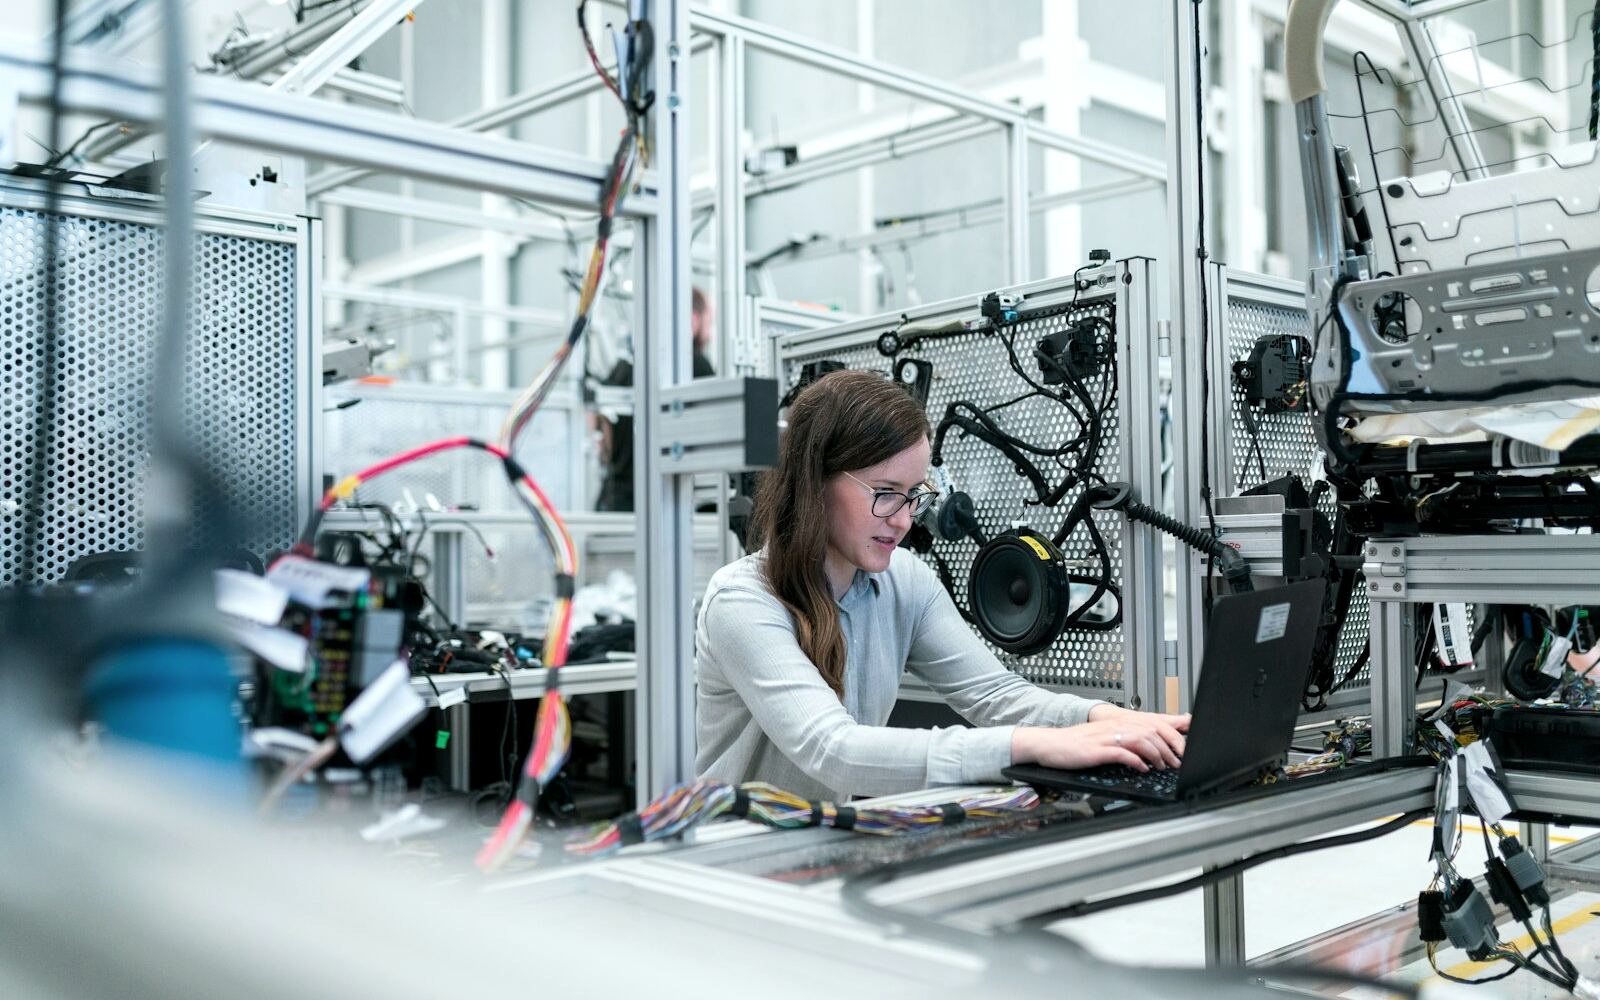
Raw materials, tooling, and shop labor ahead of shipments.
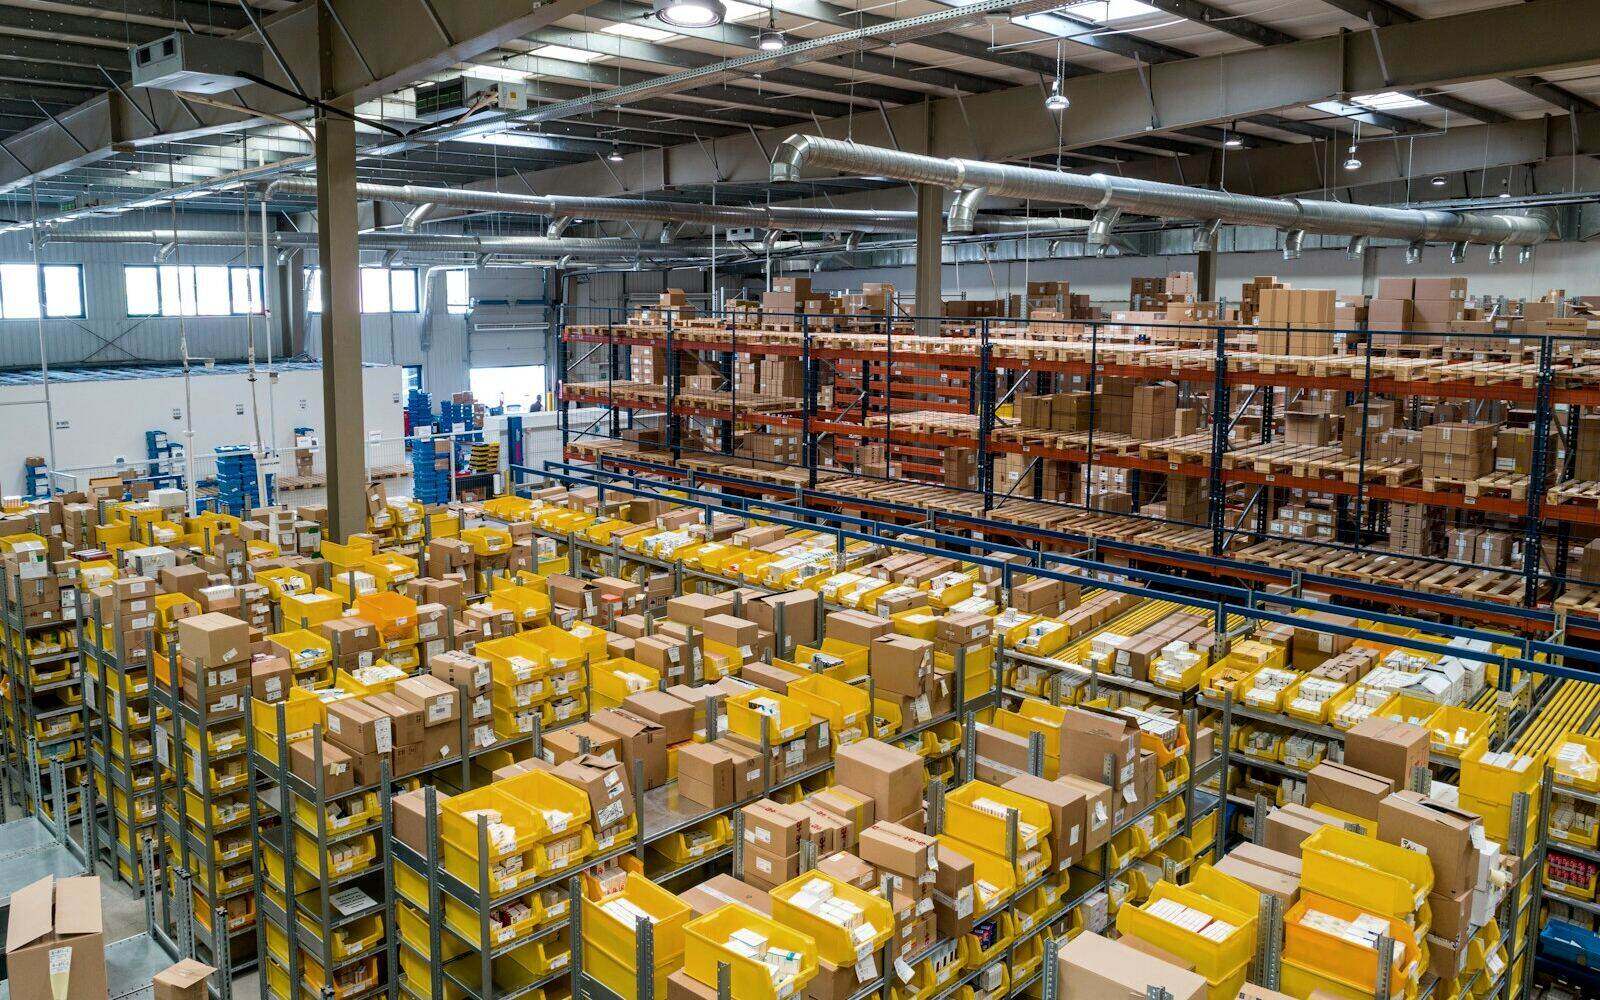
Stock the warehouse before buyers cut purchase orders.
Parts, lifts, and bay payroll between busy weeks.
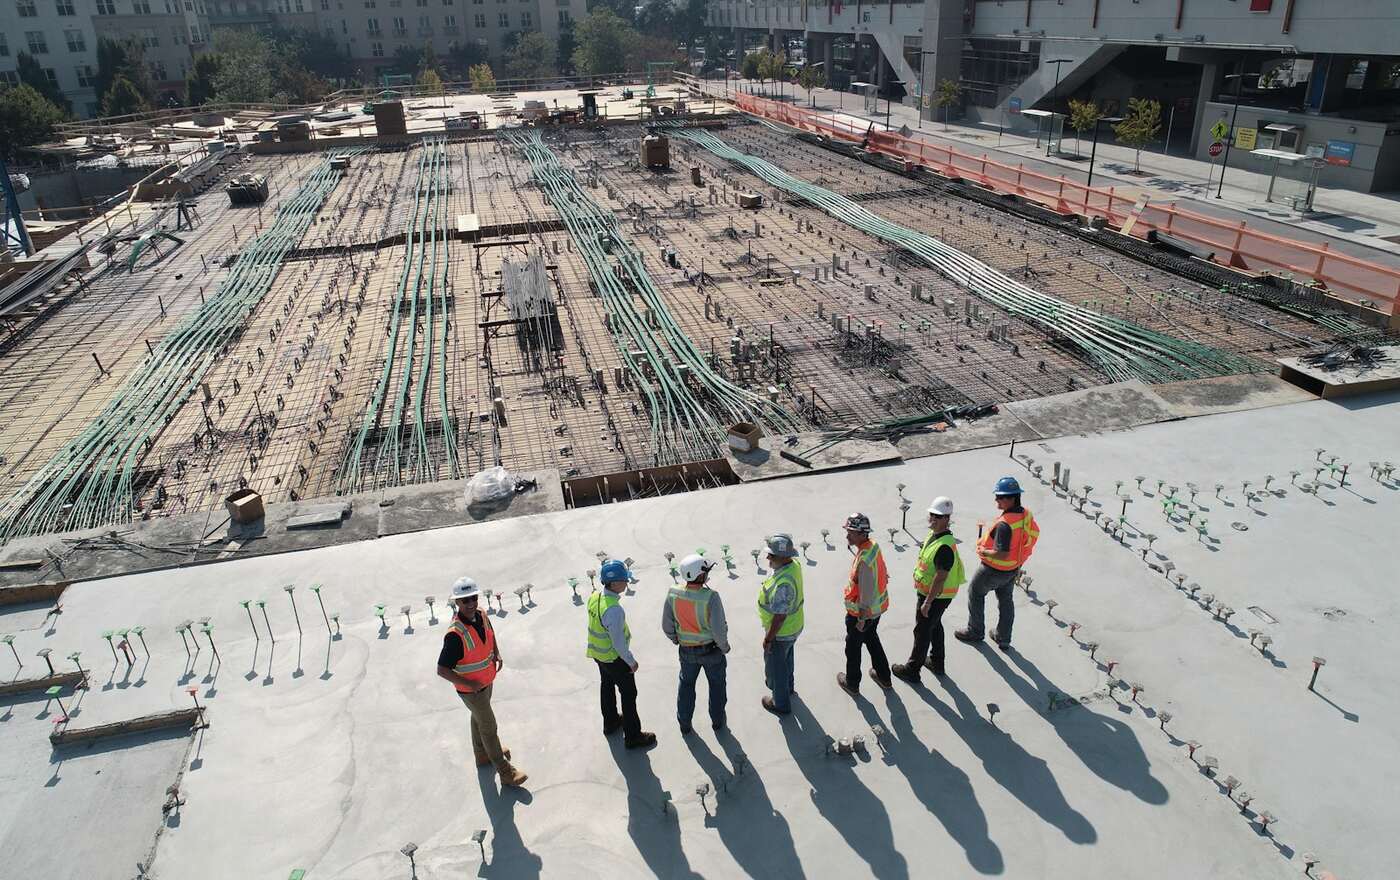
Trucks, tools, and materials before the job invoices.
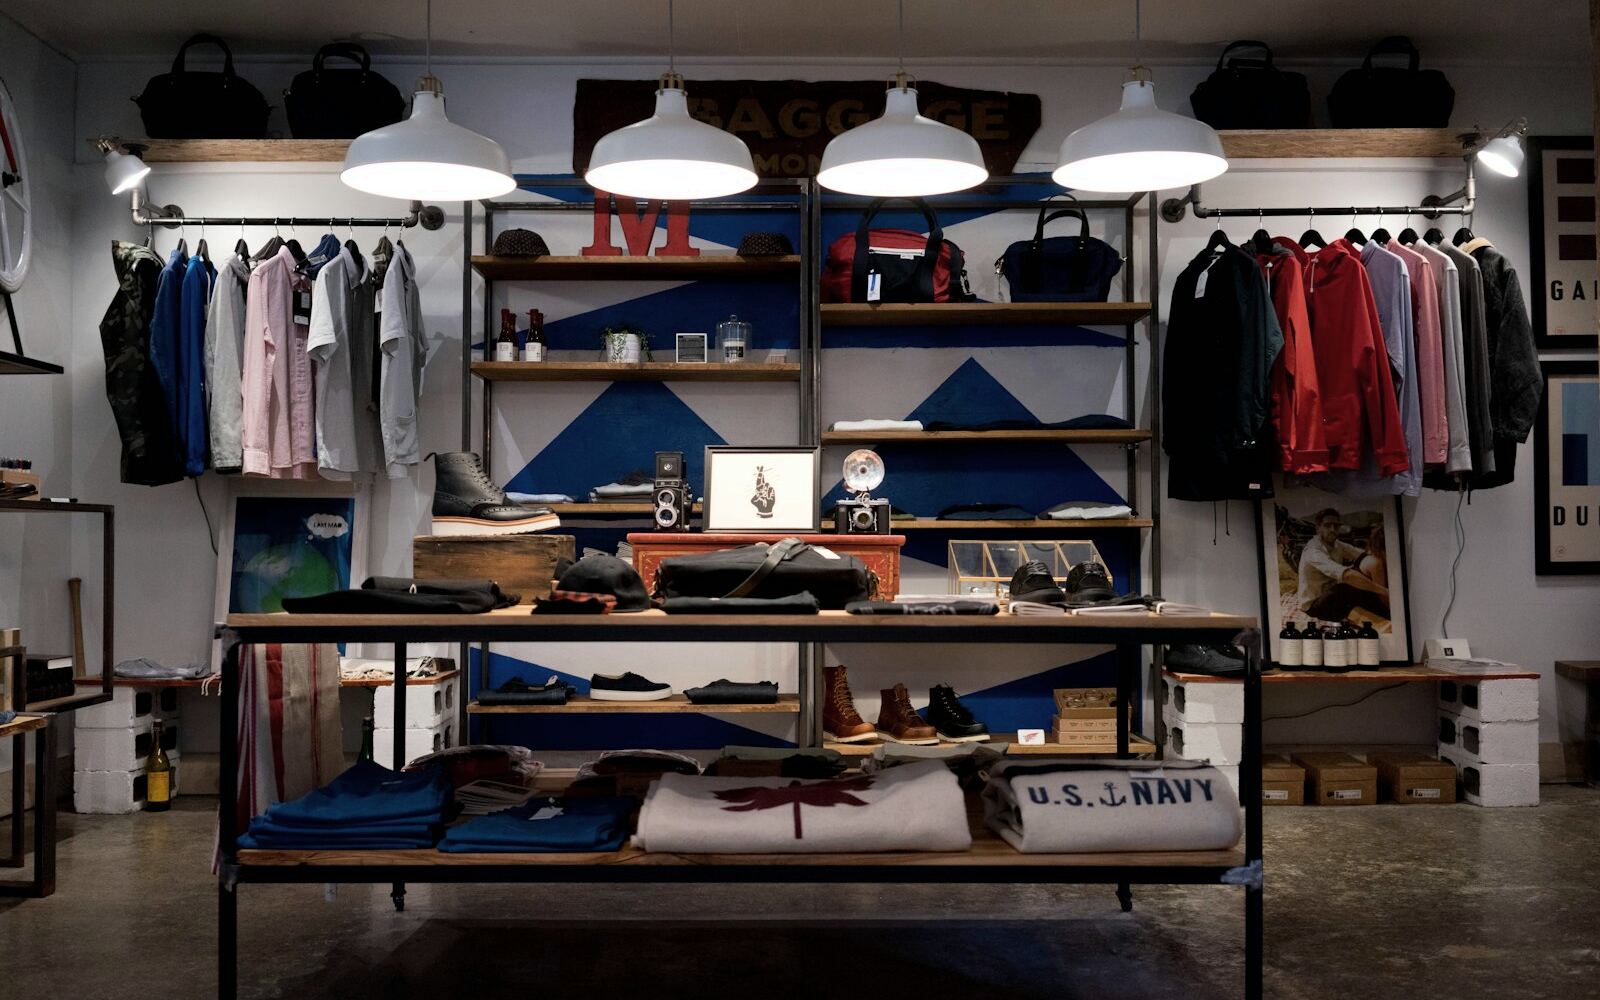
Inventory and ads ahead of the next sales cycle.
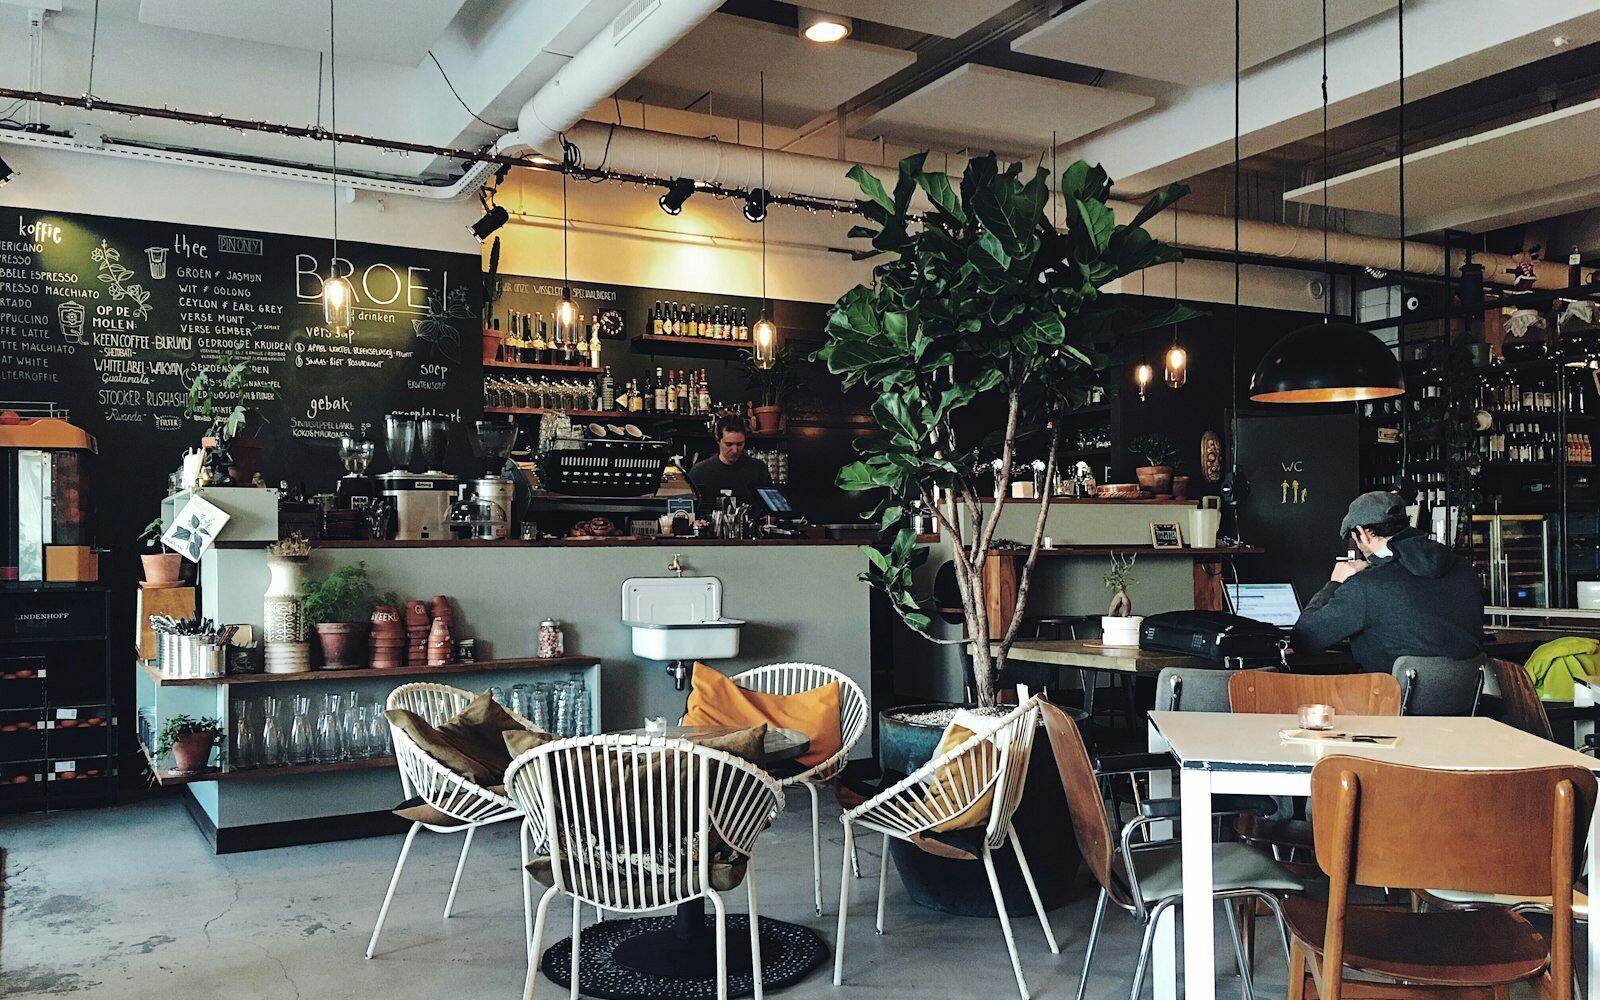
Chairs, product, and payroll between appointment peaks.
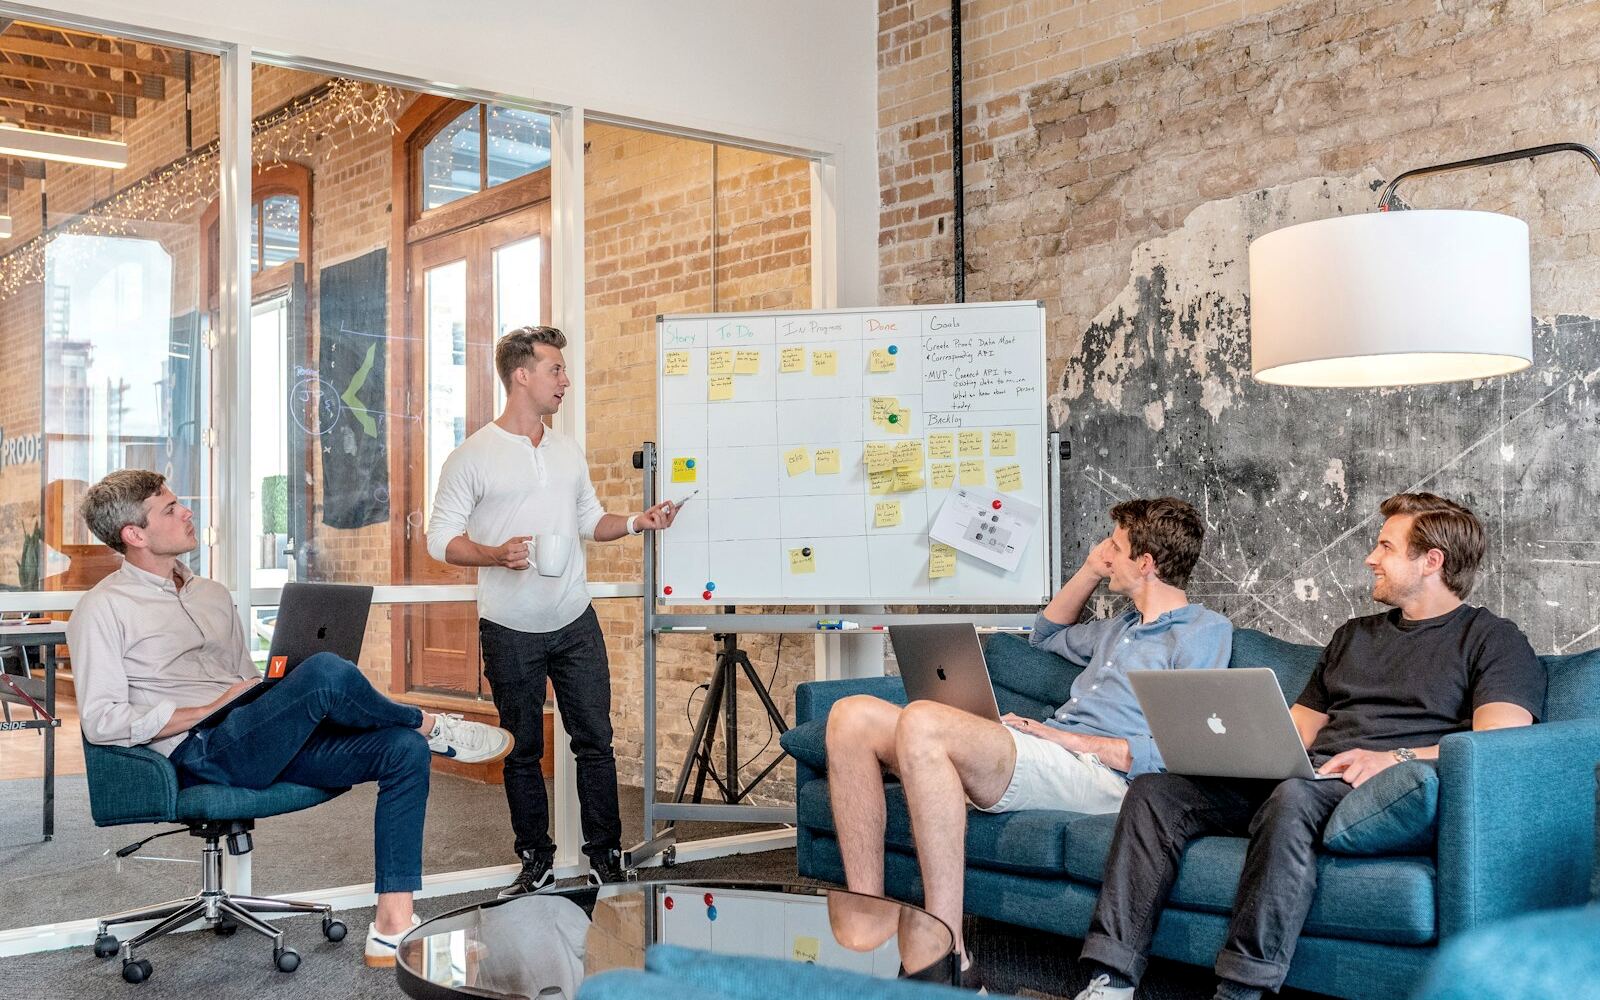
Payroll and overhead while clients pay on net terms.
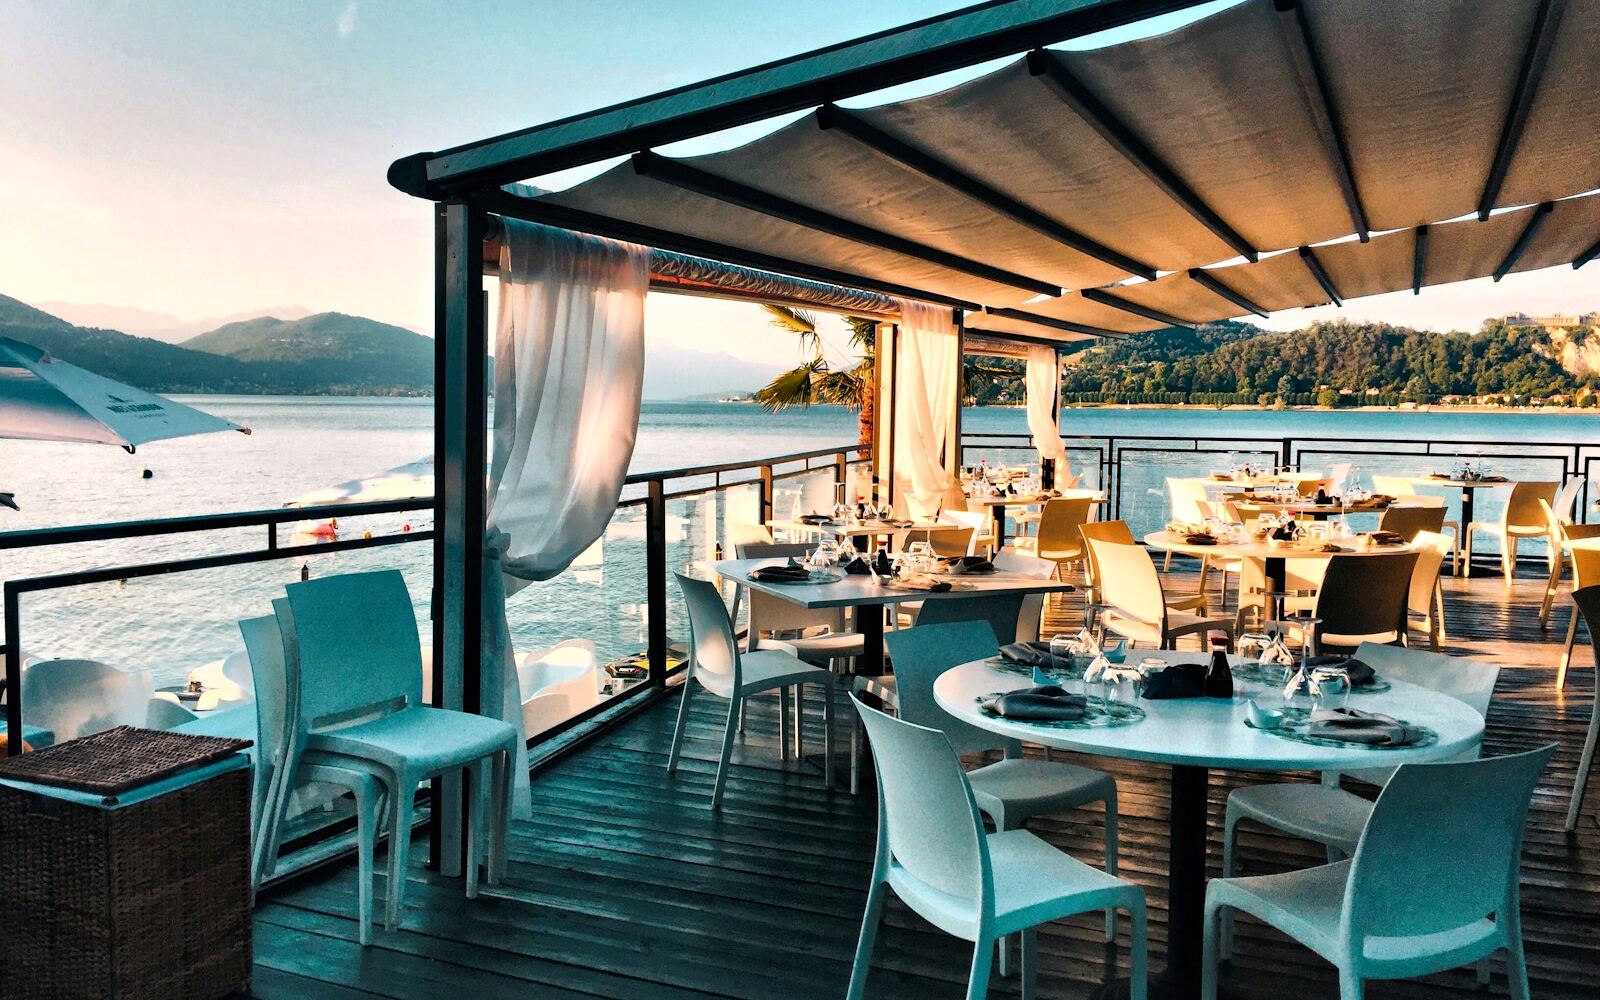
Rooms, kitchens, and seasonal staffing swings.
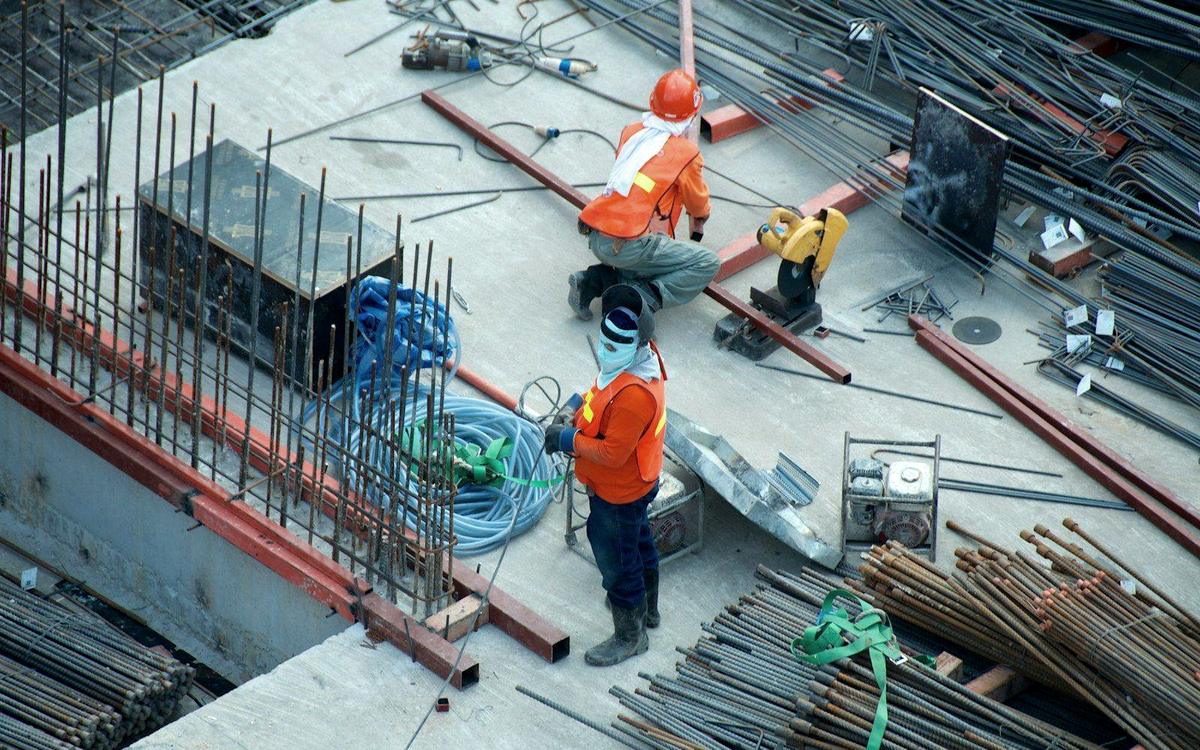
Inputs and equipment ahead of harvest or sale cycles.
Soft qualification
These are starting points — not guarantees. Banks may ask for more; some deposit-backed paths can work with less documentation and more cost.
Get options
Tell us a little about the company. A reviewer follows up with structures that fit — or a clear decline. No obligation to accept a facility.
Name, business, amount, and use of funds. Soft inquiry to start.
A reviewer follows up at the email or phone you entered. Submitting is a review request — not an offer of credit.
FAQ
It depends on deposits, existing obligations, and the product. We do not advertise a headline maximum as a promise. Share the amount you need and we size against the cash cycle.
Some deposit-backed structures move in days. Longer or SBA paths take weeks. We do not advertise a same-day guarantee.
The initial application is designed as a soft inquiry. A hard pull is not required to start. If a later product requires one, that is disclosed before it happens.
Typical starting frame: about six months in business, around $15,000 in monthly revenue, and personal credit near 500 or higher. Frames, not guarantees.
Working capital, inventory, equipment, payroll, expansion, acquisition, or refinance — as long as the use is legal and the repayment fits your deposits.
No. Oak Harbor Capital is a financing marketplace. Some facilities are issued by third-party sources. We say so before you sign.
Share a few facts about the business. Soft inquiry to start. No obligation to accept a facility.